Market intelligence:
A new stage of recovery for Hong Kong

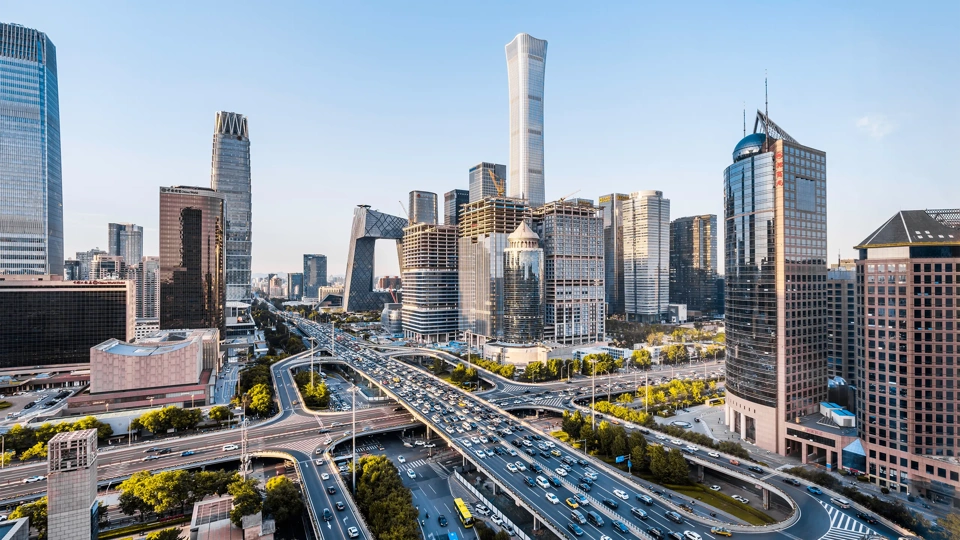


China's construction market has found firmer footing in the second half of the year. While residential construction has cooled, investment is moving decisively into data centres, advanced manufacturing, life sciences and renewables, the sectors that will define the next decade. For organisations building in these areas, H2 2026 offers competitive pricing, strong contractor availability and a supply chain built for faster, more certain delivery.
If the last year was defined by tariff turbulence and a sharp property correction, the months since have brought greater clarity about where the market is heading. The old growth model, built on rapid residential development, is not coming back in the near future. In its place is a more balanced market with direction, moving away from speculative housing and toward technology, advanced manufacturing and renewables.
“Full-year GDP growth is expected to remain in the mid-4% range, supported by advanced manufacturing and industrial investment.”
Property investment will close the year lower, but the capital behind it has not left construction. It has moved to where the growth now is.
Global conditions continue to shape project delivery, but increasingly in ways that clients can anticipate and manage. Trade tensions, shifting tariff regimes and disruptions to key shipping routes have reinforced the importance of supply chain resilience and procurement planning.
While many international markets remain vulnerable to imported material inflation, China's deep manufacturing base and extensive domestic supplier network have helped insulate projects from the worst impacts of global volatility. As a result, clients are placing greater emphasis on delivery certainty, supplier diversity and commercial risk management rather than simply pursuing the lowest upfront cost.
This market makes it unusually clear where the opportunity lies. Investment is concentrating in data centres and AI infrastructure, advanced manufacturing, semiconductors and batteries, life sciences, renewable energy and urban renewal.
“These sectors are aligned with national priorities and long-term demand, not short-term cycles.”
These are also among the most active areas for procurement, generating healthy pipelines even as traditional residential work stays subdued. For clients in these sectors, the pipeline is not only resilient but expanding.
Tendering is as competitive as it has been in years, contractor availability is strong and pricing is attractive across most tier-one and tier-two cities. Conditions are favourable, giving clients leverage, from better commercial terms to greater contractor engagement and more room to optimise value.
A sensible note of caution is that the lowest-priced bid is not always the lowest-risk choice. With certain contractors experiencing cash flow constraints, the most successful clients are balancing cost considerations with an assessment of financial resilience and delivery capability.
In this market, sound contractor due diligence protects value.
Despite the favourable conditions, delivery challenges remain, but they are increasingly well understood and manageable. China is not short of labour, but it lacks specialist skills, from commissioning, MEP and automation to the mission-critical expertise that data centres, life sciences and semiconductor facilities demand. Rather than hold the market back, this is speeding up a welcome shift toward prefabrication, modular methods and digital delivery tools that improve coordination and cut on-site risk.
“Adoption of AI-enabled digital twins, BIM and advanced analytics is becoming a competitive differentiator in China.”
Contractors are increasingly using AI-enabled tools to predict schedule delays, optimise resource allocation and identify commercial and delivery risks earlier in the project lifecycle. For clients, the benefit is not only greater productivity but improved cost predictability, programme certainty and more informed decision-making.
Regulations are evolving rapidly, with green finance requirements, smart construction guidelines, and urban renewal programmes reshaping what projects can be funded and delivered. Engaging experienced local teams early can help navigate these changes, reduce delays, and identify opportunities that others may miss.
China's core strengths as a place to build remain firmly intact. Construction steel prices remain stable and subdued, helping to keep input costs under control, while a resilient and increasingly self-reliant supply chain continues to support reliable delivery and pricing stability.
Recent disruptions to shipping routes connecting China with the Middle East and Europe have reinforced the importance of procurement planning. While freight and insurance costs have increased pressure on some imported equipment and specialist components, China's extensive supply chain and manufacturing base has helped maintain material availability and minimise project disruption.
“This has led many clients and contractors to place greater emphasis on supply chain resilience over marginal cost savings.”
Earlier procurement planning, supplier diversification and stronger visibility of critical materials are becoming standard practice. In sectors such as advanced manufacturing, semiconductors and data centres, certainty of supply is increasingly valued as highly as price competitiveness.
Where costs do shift, the movements are manageable and, with the right commercial approach, straightforward to plan around. Low, predictable costs and dependable material supply continue to make China one of the region's most affordable and deliverable markets to build in.
With conditions this competitive, the real premium has shifted to certainty. Clients want confidence on cost, strong commercial and risk management, tight programme controls and sound project governance. We’re seeing them engage earlier in scenario modelling, commercial management and project controls, because early rigour is what turns a demanding market into a well-delivered project. This is how the best-positioned clients are turning today's conditions into value.
One of the clearest signs of confidence is that Chinese capital is increasingly moving outward. Faced with strong competition at home, investors and developers are taking more projects into Southeast Asia and Hong Kong. This is where local expertise and global reach become a real practical advantage.
“A client moving capital from China into overseas markets needs two things: an accurate read of the home market and delivery capability in the destination, where contract forms, approval regimes and supply chains all differ.”
The challenge is not identifying opportunities, but translating them into projects that work in a different regulatory, commercial and delivery environment. Those teams that can connect the two ends are often best placed to bridge these different operating environments, helping investors translate opportunities into projects that are both commercially viable and deliverable on the ground.
H2 2026 will be defined by technology, industrial investment and delivery certainty rather than property and that is a more durable foundation than the cycle it replaces.
While global volatility has not disappeared, its impact is increasingly concentrated around logistics, procurement and risk management rather than broad-based project disruption. Clients that understand these risks and plan for them early are finding that China's construction market remains remarkably resilient, supported by deep supply chains, strong contractor capacity and continued investment in high-growth sectors.
The fundamentals still support well-placed investment, with competitive costs, a stable supply chain, strong contractor availability and a clear line of sight to the sectors driving growth. 'For investors, the opportunity is becoming easier to define.Focus on the growth sectors, build strong local delivery teams and prioritise certainty in procurement and controls. For those able to read the market closely and combine local insight with global delivery capability, volatility is giving way to something far more valuable: direction.
Sign up for our quarterly newsletter - trends, market intelligence and expert perspectives.
Sign up for our quarterly newsletter - trends, market intelligence and expert perspectives.